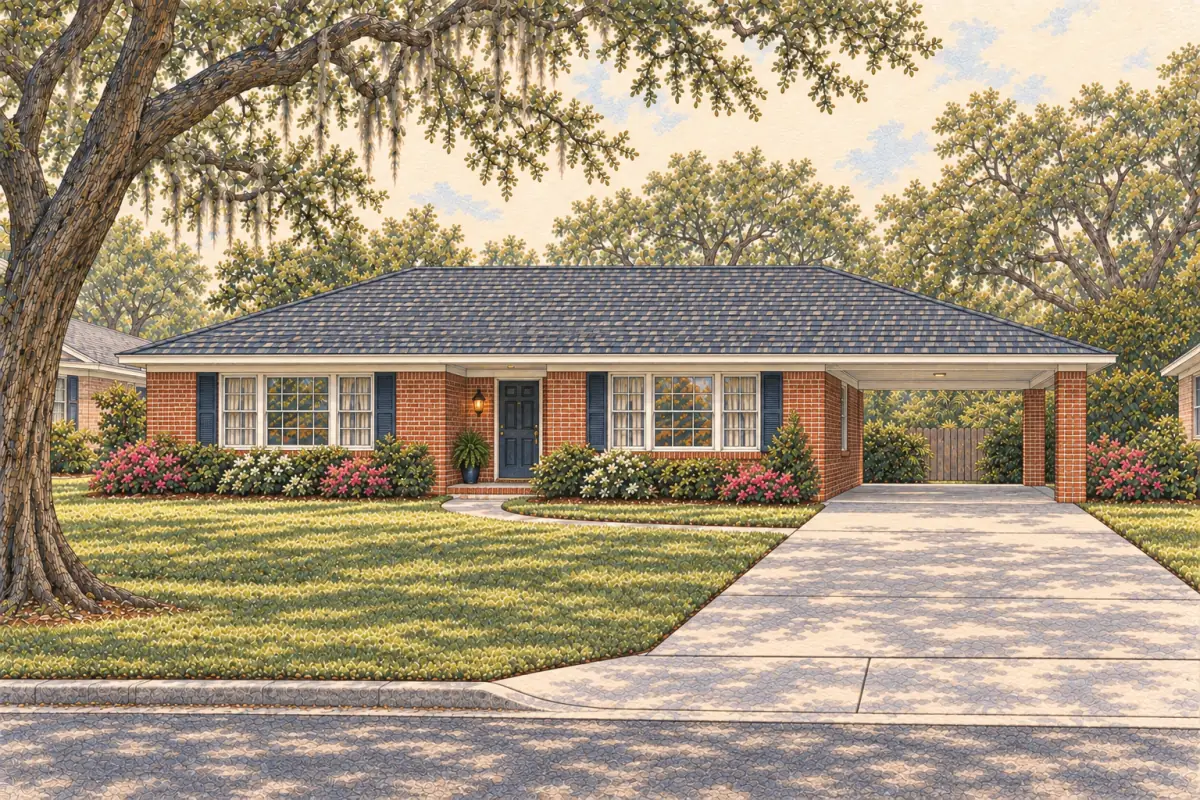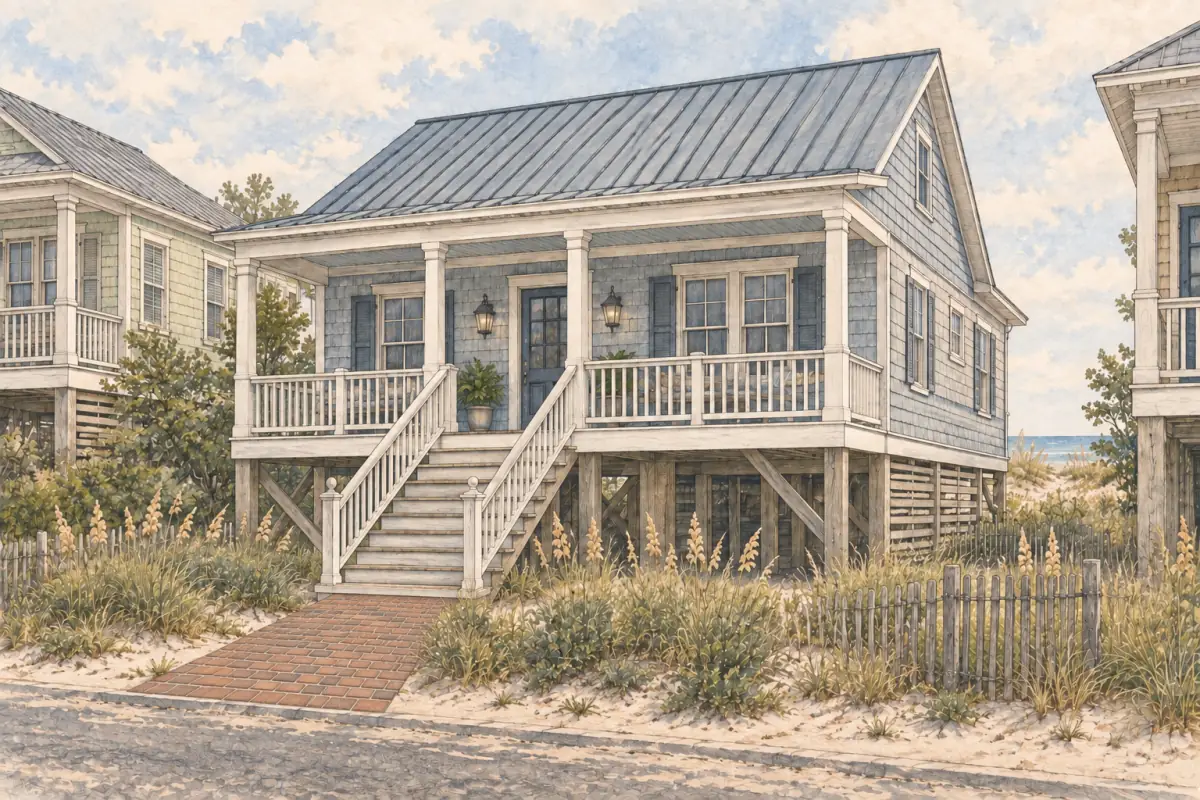
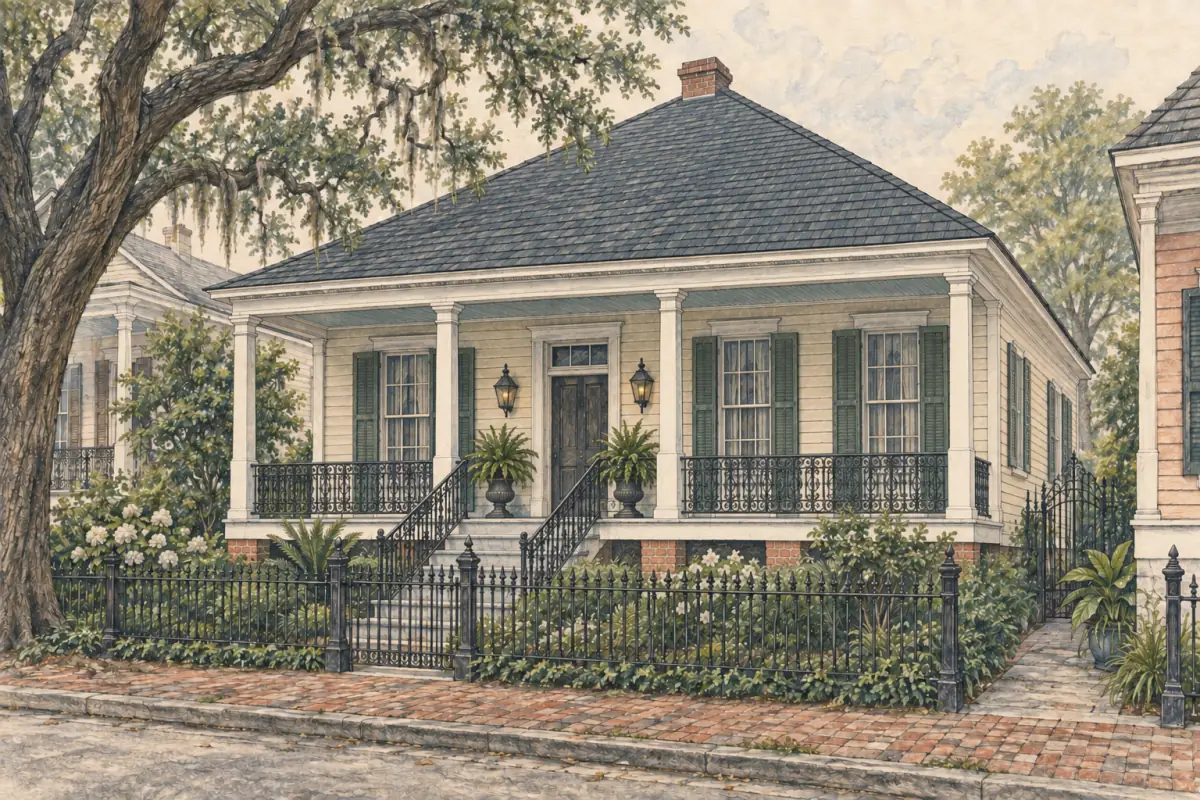
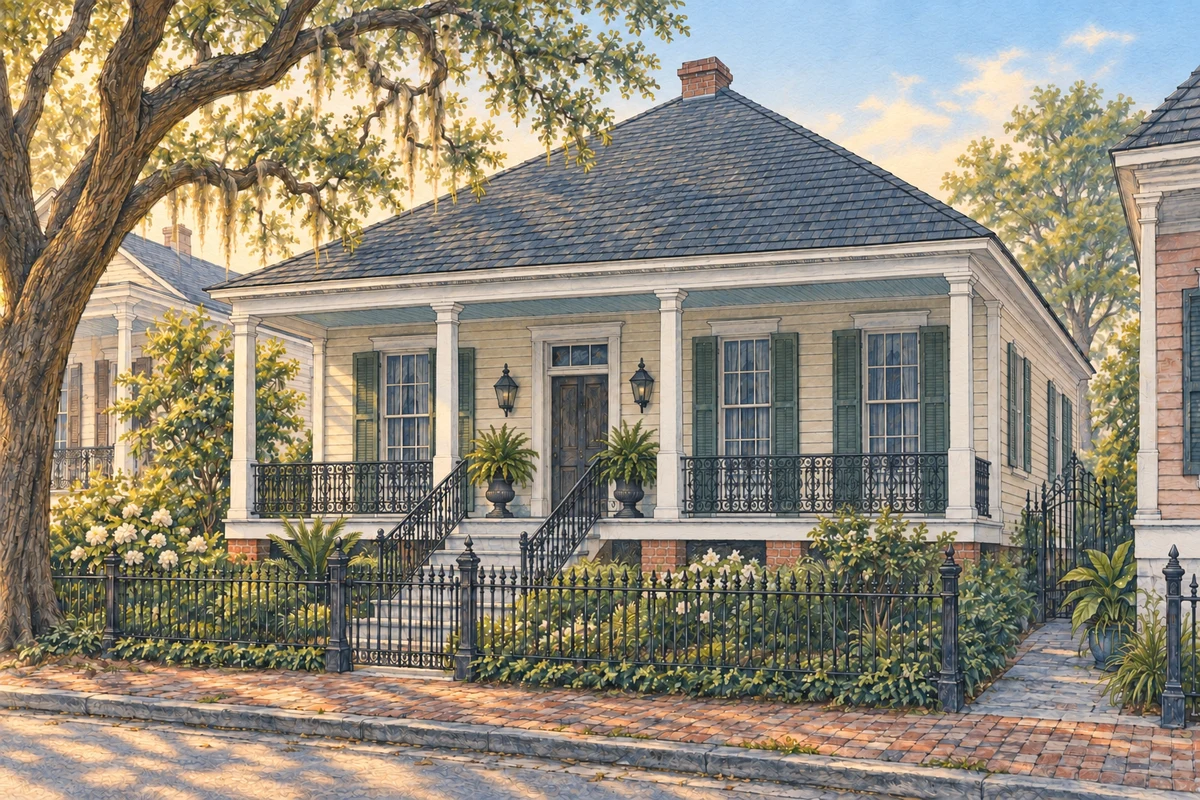
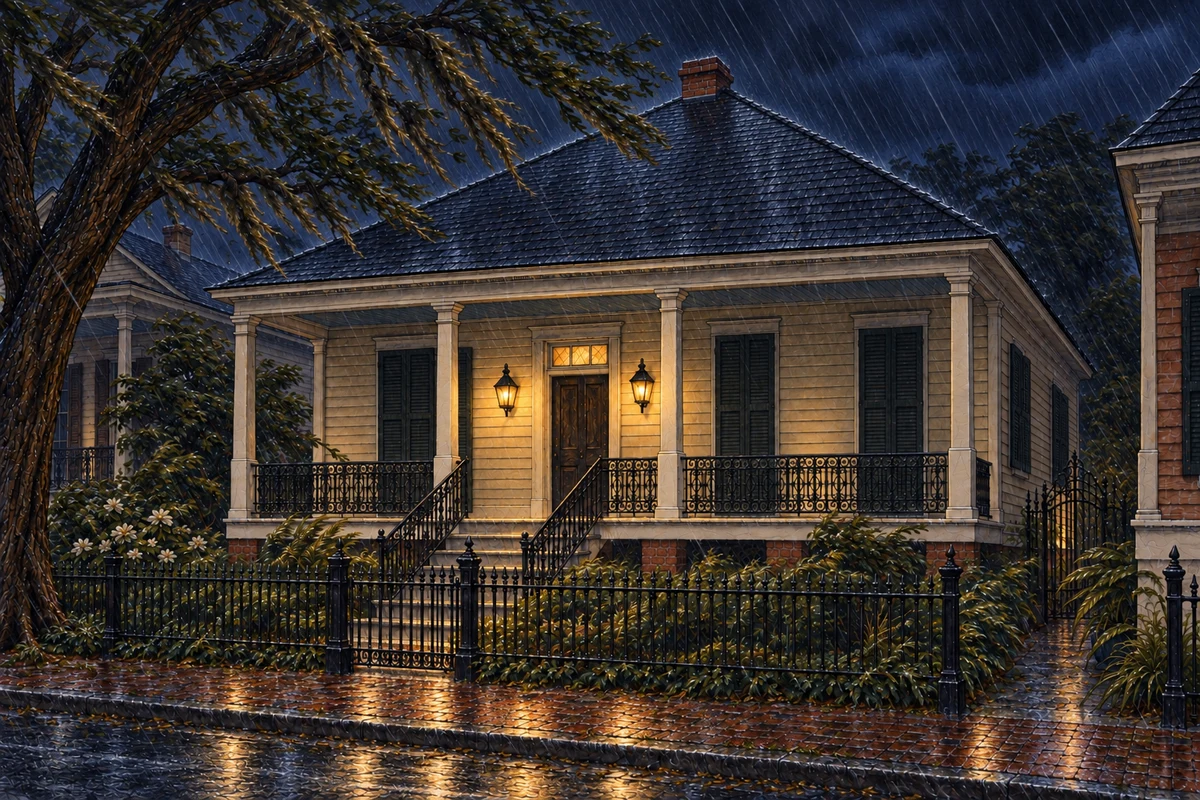
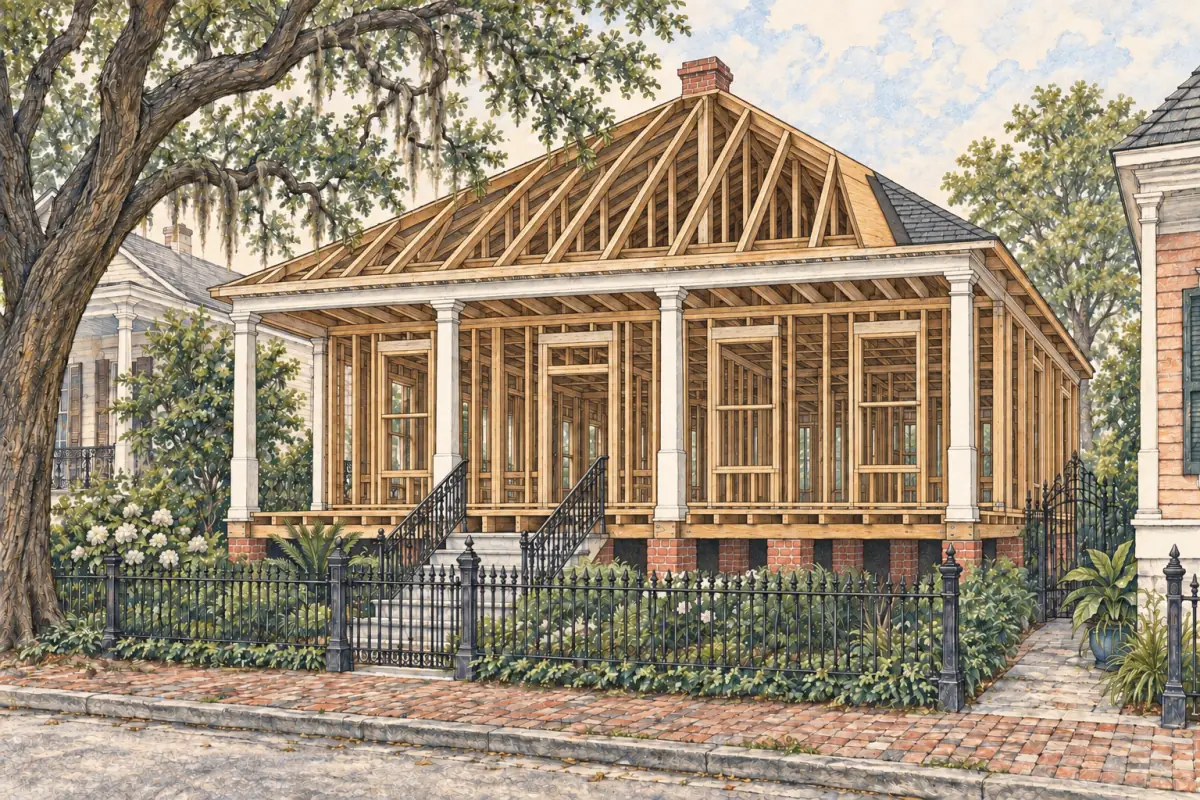
Start with the roof.
Stronger roof attachments, sealed decking and wind-rated roof coverings help resist wind and keep rain out.
Launching Early 2027 · AL, LA, NC
We specialize in Wind + Hail insurance for FORTIFIED™ homes.
We model how your home will hold up in a storm. The stronger it is, the less damage we expect and the less you should pay for insurance.
Atlas connects how your home is built to what you pay for insurance.
We estimate storm damage and repair costs for your home. Resilience is part of the price, not a discount added afterward.
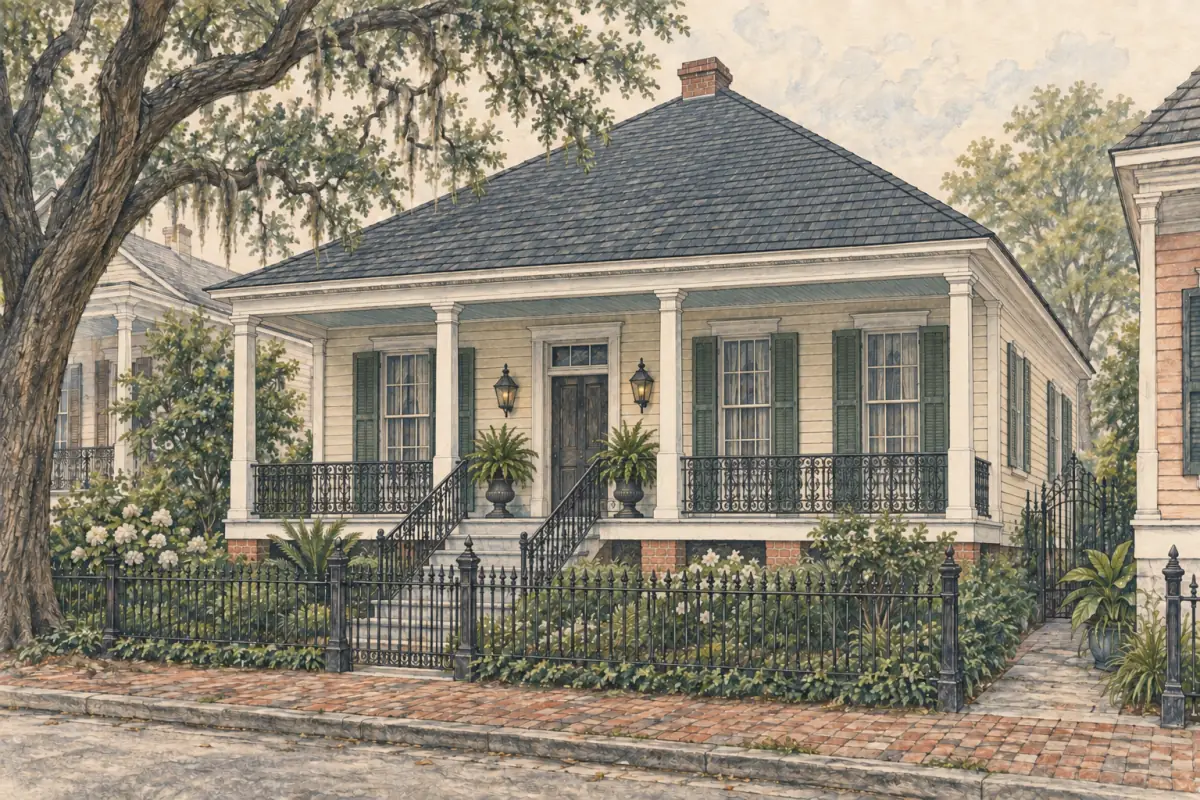
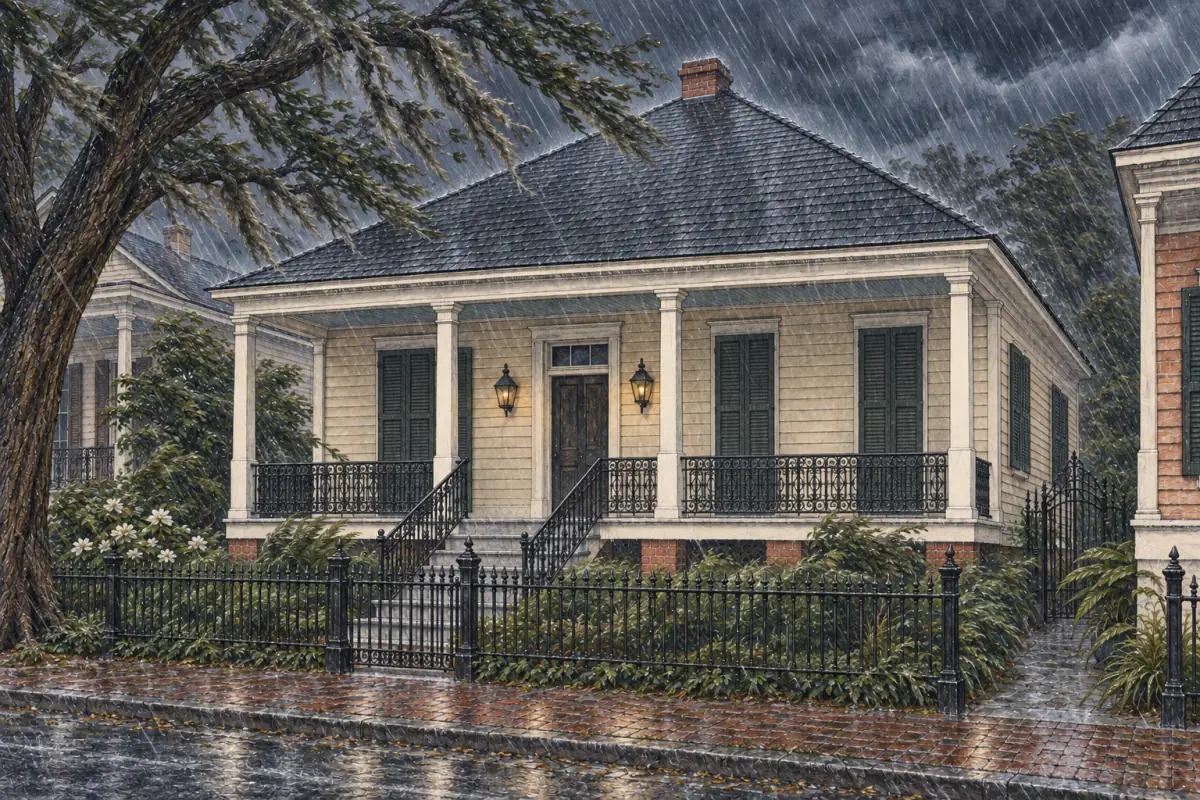
The construction
We use construction records, imagery and inspections to model how the roof is attached, how openings are protected, and how the structure connects to the foundation.
An illustration of our approach, not a live simulation or a verified model of this home. Models estimate risk; they do not guarantee storm performance or savings.
We specialize in Wind + Hail insurance for FORTIFIED™ homes. Our stand-alone policy covers wind and hail alongside your all-other-perils homeowners policy.
 Hurricanes /
 Hail
 Tornadoes
 Straight-line wind
 Flood
 Storm surge
Flood and storm surge are excluded. Your agent will help you choose limits and deductibles and understand how the two policies work together.
Have clients in Alabama, Louisiana or North Carolina with an existing or planned FORTIFIED™ Roof? Talk with Marc about Wind + Hail coverage and becoming appointed.
Designed to keep the roof on and the water out. FORTIFIED™ is a proven construction standard developed by the Insurance Institute for Business & Home Safety (IBHS).
Stronger roof attachments, sealed decking and wind-rated roof coverings help resist wind and keep rain out.
Everything in Roof, plus protection for vulnerable areas such as garage doors, chimneys and attached porches.
Everything in Silver, plus structural connections that tie the roof to the walls and the walls to the foundation.
In a study of coastal Alabama homes, FORTIFIED™ Roof homes performed better than nearby conventional homes.
Source: Performance of IBHS FORTIFIED™ Home Construction in Hurricane Sally (PDF). Alabama Department of Insurance and the Center for Risk and Insurance Research, University of Alabama, May 2025. Roof tier, nearest-neighbor analysis, tree-fall claims excluded. Loss ratios measure claims paid relative to premiums, not homeowner premium savings. Past storm performance does not guarantee outcomes in future events. Read the IBHS summary ↗
Decades in catastrophe risk, reinsurance, insurance operations, product, climate science, finance, and engineering. People who’ve built institutions and built products used by millions of customers.
Help us build the models, software and operations behind the coverage.